

 Phoenix 24
Scarcity grows stronger when ordinary investors are invited in.
Hawthorne, March 2026
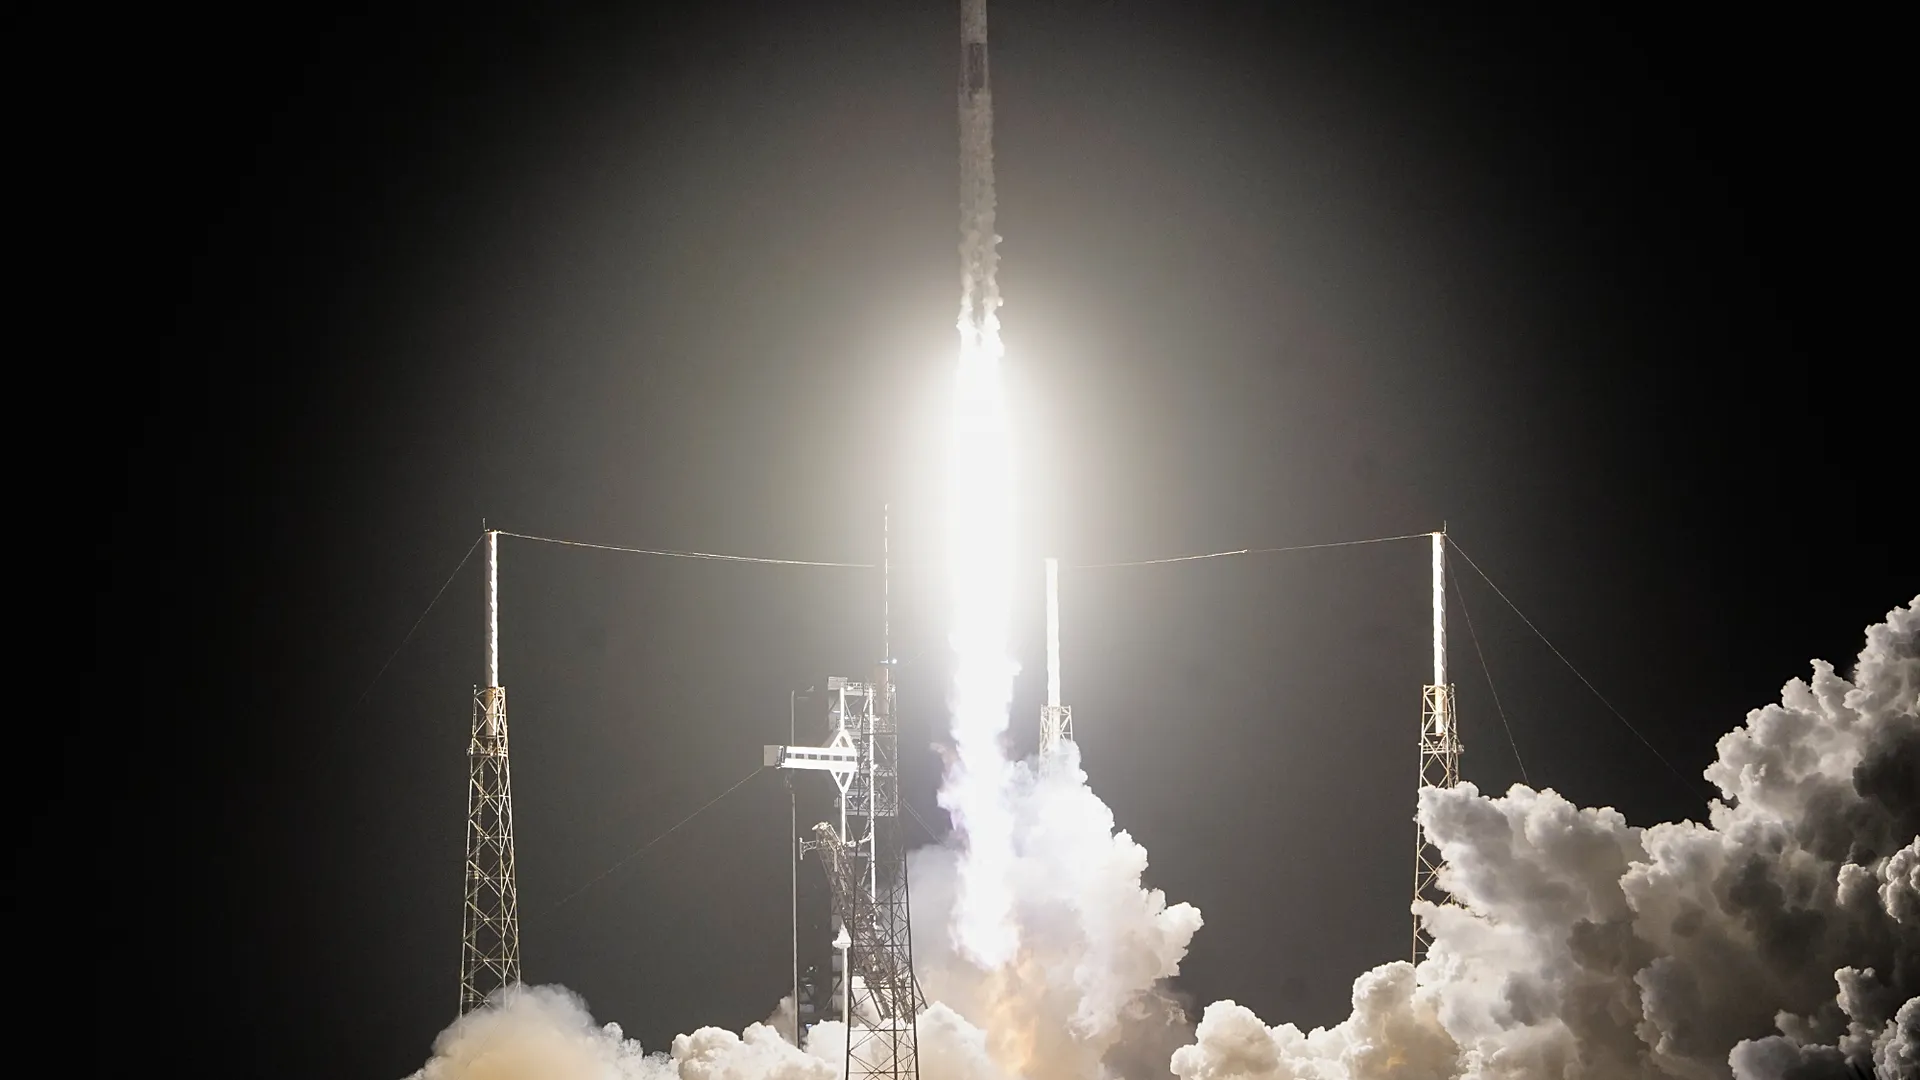
SpaceX’s reported plan to reserve as much as 30 percent of its eventual public offering for retail investors is not just a financing detail. It is a deliberate attempt to rewrite the politics of a mega-listing by giving small investors a much larger slice than is typical in major U.S. offerings. The move has been described as unusually generous by market standards and tied to a valuation discussion of enormous scale. That alone turns the offering into something bigger than a normal debut. It becomes a test of how finance, fandom and access now merge in the platform age.
What makes the move significant is not only its size, but its message. Elon Musk appears to be betting that SpaceX can turn public enthusiasm into a stabilizing force by giving ordinary investors a direct stake in one of the most anticipated listings in years. That kind of structure does not just broaden participation. It also helps shape the shareholder base from the beginning, potentially reducing the dominance of institutions and limiting the kind of early churn that can follow a major flotation. Democratization and price management, in this case, seem to be moving together.
That changes the usual public offering script. Large listings in the United States are normally structured to favor institutions, wealthy clients and tightly managed allocations that preserve elite control over early upside. A retail carve-out of this scale challenges that convention, but it also converts access itself into a marketing engine. The more a company signals room for small investors, the more it can intensify public desire to get in before scarcity closes again. In other words, inclusion can function as both financial design and narrative strategy.
There is also a deeper Musk logic behind the structure. SpaceX is not entering public markets as a quiet industrial company with limited emotional pull. It is entering as one of the most symbolically charged firms in the world, surrounded by an audience that already treats Musk-linked ventures as more than ordinary businesses. That means the offering can be imagined not just as a capital event, but as a mass-attention event where speculation, identity and loyalty begin to overlap. SpaceX would not simply be selling stock. It would be selling belonging.
Still, the retail-friendly framing should not be romanticized too quickly. Terms in a deal of this size can shift, and headline percentages often function partly as strategic signaling before the final structure is settled. That means the promise of access may be doing some of the work even before access is fully formalized. In modern markets, anticipation is itself a tradable asset. A company this magnetic does not need certainty to generate momentum.
The larger significance lies in what this says about the next phase of public markets. If a company as culturally powerful as SpaceX can bring retail investors into a giant offering at this scale, it may pressure other issuers to make similar gestures or at least to appear less exclusionary. But it also risks deepening the fusion of finance, celebrity and speculative identity that already defines much of the retail trading era. A broader invitation does not automatically make the market more equal. Sometimes it simply makes the spectacle bigger.
So the real story is not just that Musk may reserve up to 30 percent for small investors. The real story is that SpaceX appears ready to turn its public offering into a cultural event where allocation policy doubles as image management and demand generation. If that structure holds, the listing will test more than appetite for aerospace equity. It will test how far modern markets are willing to blur the line between ownership and fandom. And in that blurred zone, scarcity may become even more profitable precisely because it looks more democratic.
Detrás de cada dato, hay una intención. Detrás de cada silencio, una estructura.
Behind every datum lies an intention. Behind every silence, a structure.