

 Phoenix 24
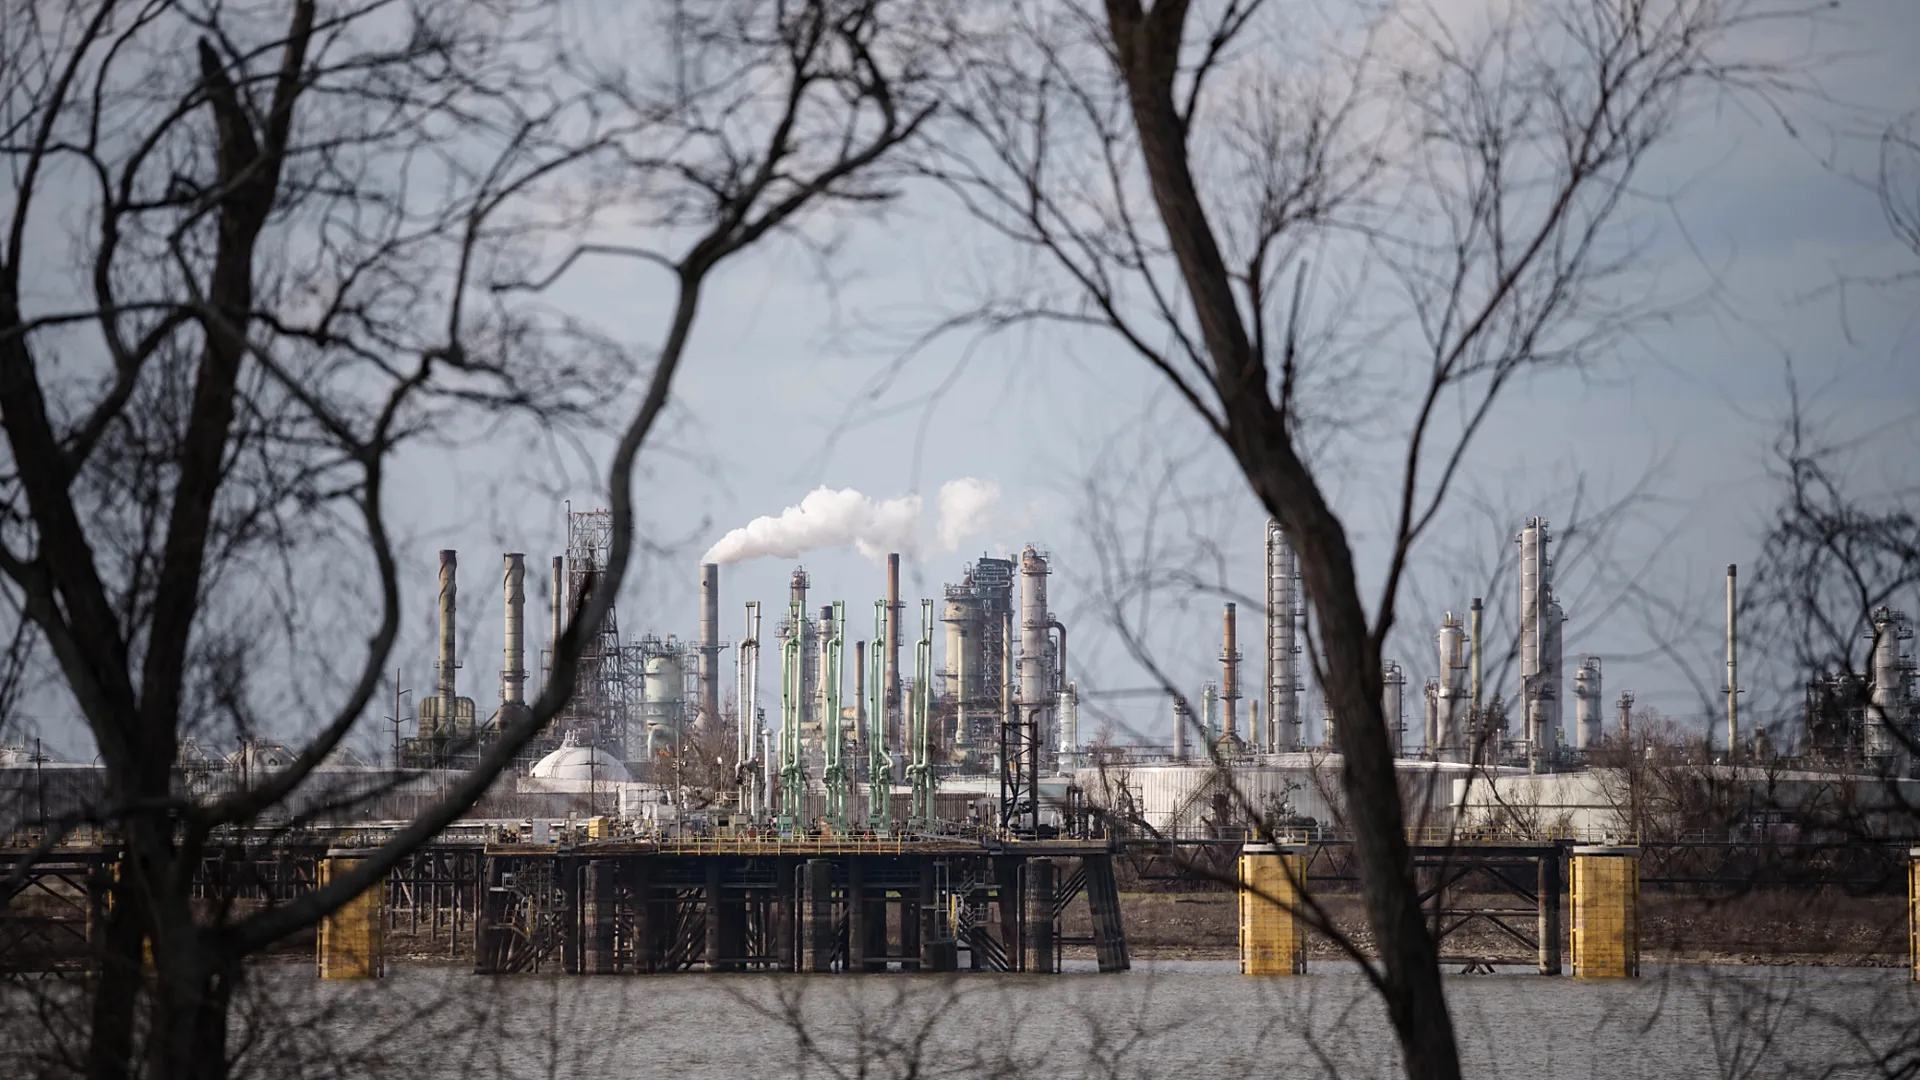
Energy panic moves faster than missiles.
Brussels, February 2026.
The immediate fear after the United States strike on Iran is military escalation, but for millions of households the first shock may appear somewhere much more ordinary: the fuel pump. That is how modern conflict often works when it touches a strategic energy corridor. Even before supply is physically interrupted, markets begin pricing risk, insurers reassess exposure, shipping firms recalculate routes, and traders add a premium for uncertainty. By the time governments issue calls for restraint, consumers can already be paying for a conflict they do not yet fully understand.
The core mechanism is simple, even if the market behaves in complex ways. Iran sits near one of the most sensitive chokepoints in the global oil system, and any confrontation that raises the possibility of disruptions in or around the Strait of Hormuz immediately changes expectations across energy markets. A large share of seaborne crude and related energy flows moves through that corridor, so the market does not wait for a confirmed shutdown to react. It responds to probability, and probability alone can move prices sharply when tensions involve state militaries, missile capabilities, and threats to maritime security.
That is why analysts and banks began discussing upside risk for crude prices as tensions intensified, even before the latest strikes fully reset the regional risk environment. In practical terms, a jump in benchmark oil prices does not translate one to one into pump prices overnight, but the pass through can be fast if the move is sudden and sustained. Refiners, distributors, and retailers absorb some volatility for a time, yet prolonged geopolitical stress tends to work its way through the chain. The public sees this as expensive gasoline. The system experiences it as a repricing of transport, insurance, logistics, and inventory risk.
The phrase that the cost of filling a tank could double is dramatic, but it becomes more plausible under specific conditions, not merely because a strike occurred. A short spike in crude prices may cause noticeable increases without reaching that threshold. A broader doubling at the pump would usually require a combination of factors: prolonged disruption fears, actual supply losses, tighter refining margins, shipping delays, elevated insurance premiums, and political hesitation in major producing states. In other words, the real danger is not one headline event but a chain reaction in which each layer of uncertainty reinforces the next.
Europe watches this closely because it is exposed in multiple ways at once. The issue is not only direct fuel prices for drivers. Higher oil prices can push transportation costs up across the economy, pressure inflation expectations, raise industrial input costs, and complicate monetary policy decisions just as some economies are trying to stabilize growth. For governments already navigating fiscal strain and social fatigue, an energy shock linked to war risk can become a political problem very quickly. What begins as a foreign policy crisis can mutate into a domestic legitimacy test within days.
There is also a psychological dimension to energy markets that is often underestimated. Consumers do not respond only to the posted price. They respond to anticipated scarcity, media intensity, and the feeling that events are moving beyond civilian control. This can accelerate demand behavior, hoarding patterns, and public anxiety, especially in countries where living costs remain a sensitive electoral issue. In that sense, the fuel pump becomes an amplifier of geopolitical stress, translating strategic uncertainty into a daily ritual of visible economic pressure.
At the same time, the market is not a one direction machine. Producers in the Gulf can adjust output, strategic reserves can be used, shipping routes can be rerouted when possible, and some of the early price spike may reflect precautionary buying rather than permanent supply damage. Traders also reverse positions quickly when escalation fears recede. That means the difference between a painful increase and a severe consumer shock depends on duration, not just intensity. A volatile week can hurt. A volatile month can reshape policy. A volatile quarter can alter growth forecasts and political narratives across regions.
What matters now is the convergence between military escalation and maritime uncertainty. If the conflict remains contained and shipping continues under heightened security, price pressure may stay elevated but manageable. If threats around critical transit routes become operational rather than rhetorical, the market reaction could become much more aggressive, and the idea of dramatically higher pump prices would no longer sound exaggerated. The line between these scenarios is thin because energy markets trade on confidence, and confidence disappears faster than production capacity can be replaced.
The deeper pattern is that energy dependence still governs strategic vulnerability, even in an era saturated with digital narratives and financial abstraction. A strike in the Middle East can still reorder household budgets in Europe within days because the infrastructure of modern life remains tied to oil flows, maritime routes, and risk pricing systems that react instantly to war signals. The public sees a higher bill. Behind it sits a global machine measuring fear in barrels, shipping lanes, and probabilities.
Phoenix24: clarity in the grey zone. / Phoenix24: claridad en la zona gris.