

 Phoenix 24
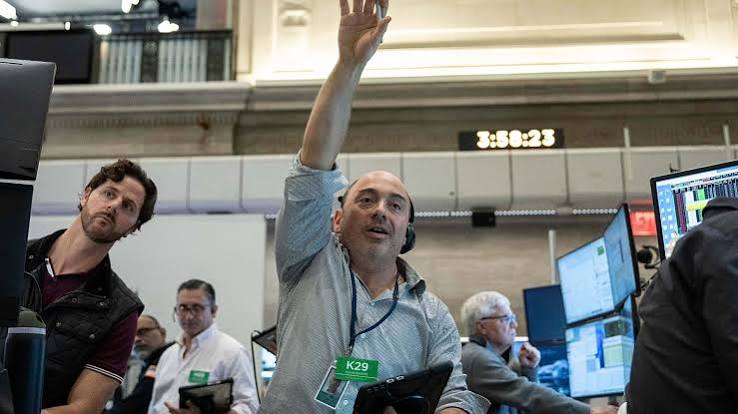
Political change in Washington redraws Europe’s market landscape.
BRUSSELS
European stock markets experienced a sharp shift in investment preferences following the United States midterm elections, as Democratic victories in both chambers of Congress prompted investors to reassess the outlook for artificial intelligence, banking, defense and energy. Despite relatively modest changes in major indexes, individual industries recorded substantial gains and losses, revealing how American political developments can influence corporate valuations far beyond US borders.
Between November 3 and November 6, the pan-European STOXX 600 gained just 0.4%, despite advancing 1.8% immediately after the election. The Euro STOXX 50 followed a similar trajectory, initially rising 2% before ending the period approximately 0.4% higher.
Those limited index movements concealed substantial differences between sectors.
European banking shares advanced 3.2%, while travel and leisure companies gained 3.9%. Utilities and healthcare stocks also attracted investment, rising 2.5% and 2%, respectively. Technology shares, by contrast, declined 3.6%, while energy companies lost 4.2%.
The banking sector benefited from stronger corporate earnings and renewed investor interest in financial institutions. Spain’s BBVA gained 5.7%, while Dutch payment processor Adyen advanced 8.9%, recovering some of the losses recorded earlier in the year.
Technology companies faced different pressures. Investors became increasingly concerned that changes in American state governments and local opposition to data centers could slow the expansion of artificial intelligence infrastructure.
These concerns affected European businesses supplying essential components to the industry. German semiconductor manufacturer Infineon declined 12.7%, while Dutch chipmaking equipment supplier ASML lost 7.3%. Nokia and Siemens Energy also experienced substantial reductions in their market valuations.
The losses reflected expectations about future demand rather than confirmed cancellations of major infrastructure projects. Slower permitting processes or additional restrictions could influence investment decisions, but their eventual economic consequences remain uncertain.
Defense companies encountered another source of volatility. Germany’s Rheinmetall fell 19.1% during the period, reflecting concerns about future military expenditure alongside a separate company announcement reducing its 2026 revenue forecast.
The distinction is significant: the share-price decline cannot be attributed exclusively to the American election because Rheinmetall also faced company-specific operational challenges.
Bond markets registered corresponding adjustments. Germany’s benchmark 10-year government bond yield declined from 3.33% to 3.25%, while US Treasury yields also retreated as investors reconsidered inflation, government spending and economic growth expectations.
For European financial markets, the episode illustrates how political events can influence different industries through contrasting expectations about regulation, public expenditure and international trade.
However, market reactions should not be confused with established economic outcomes. The incoming US Congress will not assume office until January 2027, and the practical consequences of future legislation remain undetermined.
The broader significance lies in Europe’s interconnected exposure to American policy. Even when major stock indexes appear stable, changing expectations about technology, defense and energy can redistribute investment across entire sectors.
Beyond the Numbers, the Consequences.