

 Phoenix 24
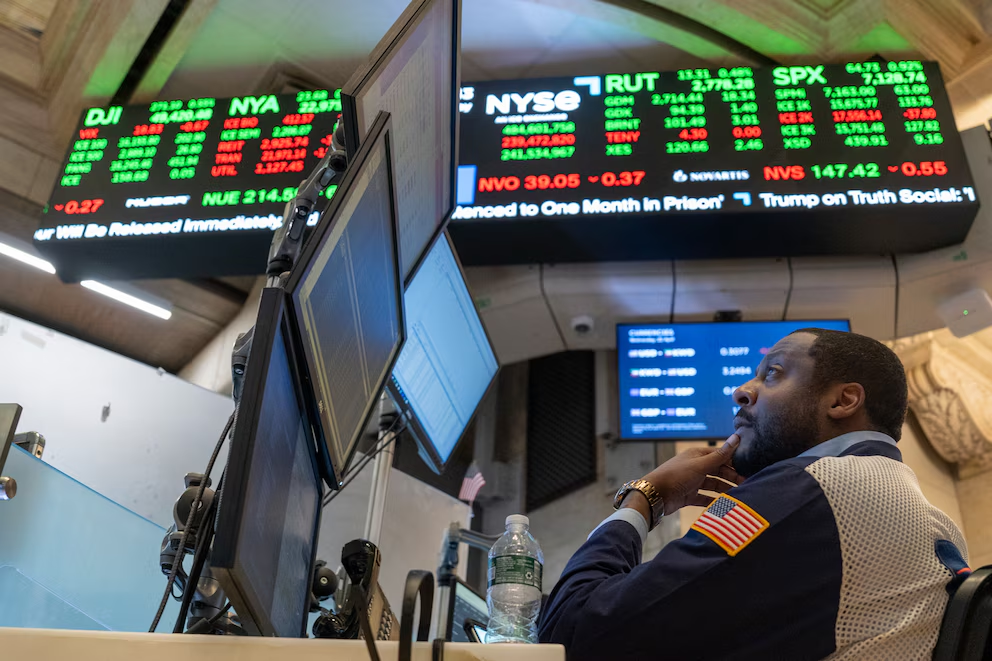
The artificial intelligence boom faces its defining financial test.
NEW YORK
The global artificial intelligence industry is entering a decisive phase as unprecedented investment in data centers, advanced semiconductors and computing infrastructure encounters growing scrutiny from financial markets. Spending estimates and investment commitments across major technology companies have reached the trillion-dollar scale, while investors increasingly demand evidence that these expenditures can generate sustainable revenue, operating profits and positive cash flow. A sharp technology selloff on November 20 exposed the tension between expectations of transformative technological growth and the financial realities of building an increasingly expensive AI ecosystem.
The market reversal was particularly severe. The Nasdaq Composite fell 5.3%, while the S&P 500 declined 3.7%, reflecting widespread concern about technology valuations and the sustainability of the industry’s investment cycle. Nvidia lost approximately 14% of its market value during the session, following a Reuters report that US securities regulators were examining aspects of the company’s accounting practices. The reported investigation does not establish misconduct, but it intensified existing uncertainty surrounding one of the most influential suppliers of artificial intelligence infrastructure.
Anthropic’s historic stock market debut offered another indication of changing investor expectations. The developer of the Claude AI assistant raised approximately $81.3 billion in its initial public offering, pricing shares at $83 before beginning trading on November 19. Although the stock initially reached $111.50 and briefly lifted the company’s valuation toward $2 trillion, enthusiasm weakened rapidly. Shares closed the following session at $88.91, an 8.5% decline that brought the price considerably closer to its original offering level.
The company’s experience reflects a broader change in how Wall Street evaluates artificial intelligence businesses. Investors previously rewarded exceptional revenue growth, expanding computing capacity and technological leadership, often accepting substantial spending as a necessary condition for future market dominance. Increasingly, the central questions concern operating margins, the cost of serving AI customers and the time required for capital-intensive infrastructure to generate acceptable financial returns.
The scale of expenditure helps explain these concerns. JPMorgan Global Research projects approximately $900 billion in global AI-related capital spending during 2026, while estimates covering wider infrastructure categories and multiyear commitments extend into several trillion dollars. The International Monetary Fund has projected that cumulative AI-related capital expenditure could exceed $4 trillion by 2029. These figures represent different measurement periods and categories of investment, making it essential to distinguish money already spent from projected expenditure and contractual obligations.
Major technology companies are at the center of this transformation. Amazon, Microsoft, Alphabet, Meta and Oracle are directing enormous resources toward specialized processors, cloud infrastructure, networking equipment and the electricity required to operate large computing facilities. These investments are designed to satisfy growing demand for AI services, but they also create financial obligations that cannot be justified indefinitely through expectations of future adoption alone.
The pressure is particularly significant because developing advanced artificial intelligence involves costs that differ from those of conventional software businesses. Training increasingly sophisticated models requires substantial computing resources, while operating those models generates recurring expenses associated with inference, electricity, maintenance and hardware replacement. Even when customer adoption increases, profitability depends on whether revenues grow sufficiently to cover both ongoing service costs and the infrastructure needed to expand capacity.
Anthropic illustrates this challenge. According to financial information disclosed around its public offering, the company has entered into agreements involving approximately $900 billion in future computing and infrastructure commitments. Such agreements should not be confused with expenditure already completed or immediate financial liabilities of equivalent size. Nevertheless, they demonstrate how strongly frontier AI developers are committing resources to anticipated future demand.
The implications extend across the technology supply chain. Semiconductor manufacturers, data center operators, electricity providers and telecommunications companies have benefited from the infrastructure expansion, but their outlooks remain connected to the spending decisions of a relatively small number of major customers. If those companies delay construction projects or reduce equipment purchases, the effects could spread through industries that have expanded capacity in anticipation of continued AI demand.
Financial institutions are beginning to examine these risks more closely. Reuters reported that some investors have adjusted their exposure to companies dependent on AI infrastructure spending, while analysts have raised questions about increasingly concentrated market valuations. A particularly important concern involves the relationship between investment and financing, including arrangements in which technology suppliers, cloud providers and AI developers maintain overlapping commercial and financial interests.
Such relationships are not inherently problematic, but they can complicate the interpretation of market demand. Revenue generated through interconnected commercial agreements may differ economically from purchases financed entirely by independent customers. Evaluating the sustainability of the AI economy therefore requires attention to cash flows, financing arrangements and the extent to which demand is supported by profitable applications rather than expectations of continuing investment.
The debate should not obscure the technological and commercial progress already achieved. Artificial intelligence is being incorporated into software development, scientific research, customer service, healthcare administration and industrial operations. Cloud providers have reported increased demand for computing services, while enterprises continue experimenting with tools intended to improve efficiency and support professional decision-making. The unresolved issue is whether these applications will produce sufficiently broad and durable economic value to justify the extraordinary resources being deployed.
For businesses adopting AI, the emerging financial environment could encourage more rigorous evaluation of implementation outcomes. Instead of measuring success primarily through the number of deployed systems or employees using AI tools, organizations may increasingly examine productivity improvements, measurable cost reductions, service quality and the reliability of automated decisions. These assessments also need to account for integration expenses, cybersecurity, employee training and the human oversight required in consequential applications.
The economic consequences could extend beyond the technology industry. Large-scale AI infrastructure investment influences electricity demand, regional construction activity, semiconductor manufacturing and capital markets. A prolonged reduction in spending could affect these interconnected sectors, while sustained investment without adequate returns could increase pressure on corporate balance sheets and financing conditions. Neither outcome is inevitable, and continued commercial adoption could improve the financial performance of companies that successfully translate technological capabilities into profitable services.
The current market correction does not demonstrate that artificial intelligence lacks economic value or that the industry has entered an irreversible downturn. It does, however, suggest that financial markets are becoming less willing to treat technological potential as sufficient justification for continuously expanding capital commitments. The distinction between technical capability, commercial demand and realized profitability is becoming increasingly important.
Artificial intelligence may ultimately transform productivity and the organization of economic activity, but the scale of that transformation cannot be established through investment announcements or market valuations alone. For technology companies, the next stage will require demonstrating that unprecedented computing power can support businesses capable of generating durable financial and social value. The central question is shifting from how much the industry can invest to what those investments can actually deliver.
Beyond the Numbers, the Consequences.